Social Security Planning
Social Security Planning Guide for Retirees: Timing, Taxes, and Maximizing Your Benefit
Social Security is one of the most consequential financial decisions most retirees will ever make. It's also one of the most misunderstood.
The difference between claiming at 62 versus waiting until 70 can be $100,000 or more over a lifetime - sometimes significantly more when a surviving spouse's benefit is factored in. Add in the interaction with Medicare premiums, the taxability of benefits, and the coordination between spouses - and the decision becomes genuinely complex.
REVIEWED BY
Rob Field, NSSA® & IRMAA Certified Planning
National Social Security Advisor | IRMAA Certified Planner | Certified Financial Fiduciary | Nelson Financial Planning
Rob is the only Certified Financial Fiduciary in Florida to hold both the National Social Security Advisor (NSSA) and IRMAA Certified Planning designations — credentials that matter because Social Security decisions don't happen in isolation from Medicare costs and taxes.
Claiming Social Security is not a transaction - it's a strategy.
And unlike most financial decisions, it is largely permanent. Getting it right requires your specific numbers, not a general rule of thumb.
ON THIS PAGE
When to Claim: The Question Everyone Asks
The question the Nelson Financial Planning team gets more than almost any other is some version of: "When should I take Social Security?"
The honest answer is: it depends. But not in the vague, unhelpful way that sounds like a dodge. It depends on specific, calculable factors. And once you run them honestly, the right direction usually becomes much clearer than people expect.
Here's what the math actually looks like. Your Social Security benefit increases by roughly 8% for every year you delay past your Full Retirement Age (FRA) — up to age 70. That's a guaranteed, inflation-adjusted increase on a benefit that lasts for the rest of your life and forms the basis of your surviving spouse's benefit after you're gone.
The claiming window
Claiming early can make sense if you have health concerns that reduce expected longevity, if you don't have adequate income from other sources to bridge the gap, or if the breakeven analysis genuinely doesn't favor delay in your specific situation.
Your Social Security benefit increases by roughly 8% for every year you delay past your Full Retirement Age (FRA) — up to age 70.
That's a guaranteed, inflation-adjusted increase on a benefit that lasts for the rest of your life and forms the basis of your surviving spouse's benefit after you're gone.
The breakeven calculation — the age at which cumulative delayed benefits surpass what you would have collected by claiming earlier — typically falls somewhere in your late 70s to early 80s. Whether you expect to reach that age, and in what health, is a meaningful part of the decision.
But delaying isn't always the right answer. Claiming early can make sense if you have health concerns that reduce expected longevity, if you don't have adequate income from other sources to bridge the gap, or if the breakeven analysis genuinely doesn't favor delay in your specific situation.
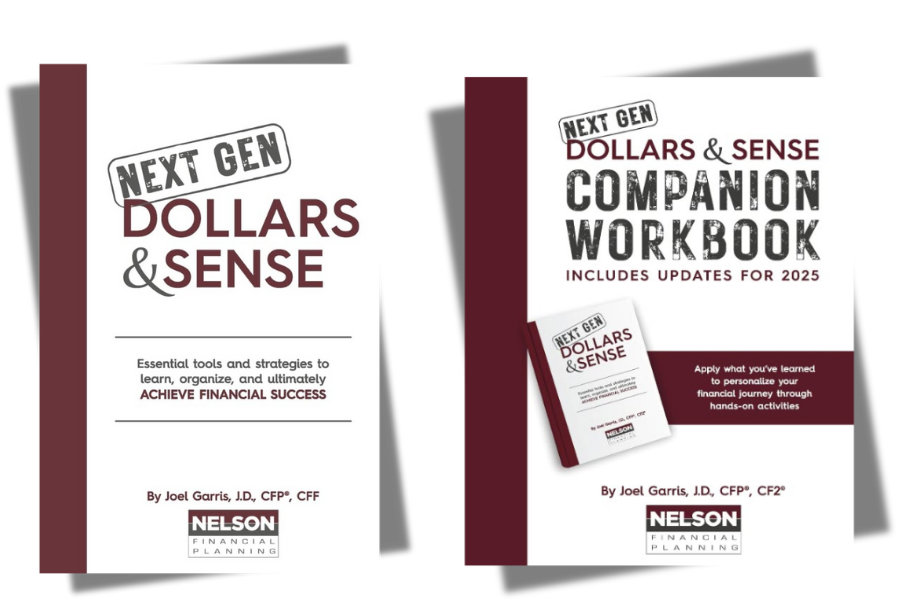
From the NextGen Dollars & Sense book and the team's work with clients: "Delaying will increase your retirement benefit by 8% each year after reaching your full retirement age if you continue to delay. That's typically a strategy we encourage for people who haven't saved enough for retirement — because it's a guaranteed, inflation-adjusted raise on a permanent benefit. But it's really important to analyze your particular individual situation. The optimal solution isn't always to delay as long as possible."
The breakeven calculation — the age at which cumulative delayed benefits surpass what you would have collected by claiming earlier — typically falls somewhere in your late 70s to early 80s. Whether you expect to reach that age, and in what health, is a meaningful part of the decision.
8% / year
Your Social Security benefit increases by roughly 8% for every year you delay past your Full Retirement Age (FRA) — up to age 70.
Late 70s - early 80s
The breakeven calculation — the age at which cumulative delayed benefits surpass what you would have collected by claiming earlier — typically falls somewhere in your late 70s to early 80s.
2026 EARNINGS TEST
$24,480
earnings limit before FRA
$1 for every $2
your benefit is reduced above that limit
If You're Still Working
Claiming Social Security before your Full Retirement Age while still working comes with an important complication: the earnings test. For 2026, if you earn more than $24,480 while collecting Social Security before your FRA, your benefit is reduced — by $1 for every $2 you earn above that limit. It's a low threshold that catches a lot of people off guard.
The earnings test goes away once you reach Full Retirement Age. But any benefit reduction during those early years is not simply lost — it gets credited back to you over time in the form of a slightly higher benefit going forward. The math on when that credit is recouped is part of the breakeven analysis.
Spousal Benefits: The Coordination Decision Most Couples Get Wrong
For married couples, Social Security isn't just an individual decision — it's a household strategy. The timing of when each spouse claims, and the interaction between each partner's benefit, can produce dramatically different lifetime outcomes depending on how it's coordinated.
A spouse who has not worked, or who has a lower earnings history, may be entitled to a spousal benefit of up to 50% of the higher-earning spouse's full retirement age benefit. But that spousal benefit cannot begin until the primary earner files for their own benefit. This creates a sequencing question with significant implications.
For surviving spouses, the stakes are even higher. When one spouse dies, the surviving partner steps into the deceased spouse's benefit — but only if it's larger than their own. The higher-earning spouse's claiming age therefore determines the survivor benefit for the rest of the surviving partner's life. Claiming too early can permanently reduce what a surviving spouse receives, sometimes for decades.
Up to 50%
A spouse who has not worked, or who has a lower earnings history, may be entitled to a spousal benefit of up to 50% of the higher-earning spouse's full retirement age benefit.
This is the calculation that Rob Field works through for every married couple: not just "when should I claim?" but "what does our claiming strategy look like as a household, and what does the surviving spouse receive under each scenario?"
Social Security & IRMAA: The Medicare Connection
Social Security income counts toward Modified Adjusted Gross Income — which determines whether IRMAA Medicare surcharges apply. This creates a direct link between your claiming decision and your Medicare costs that most people don't know to look for.
A large lump-sum payment from delaying benefits, or a significant increase in income in a given year, can push total MAGI above the IRMAA threshold and trigger higher Medicare premiums for the a full year.
Rob Field holds both the NSSA and IRMAA Certified Planning designations — credentials that specifically address this intersection. He is the only advisor within 50 miles of Orlando to hold both. The combination allows him to model Social Security claiming decisions alongside their Medicare premium implications in a way that most advisors simply aren't equipped to do.
ROB FIELD HOLDS BOTH
 National Social Security Advisor
 IRMAA Certified Planning
He is the only advisor within 50 miles of Orlando to hold both.
YOU MAY ALSO BE INTERESTED IN
Get a personalized Social Security analysis -
no cost, no obligation.
In-Depth Guides: Social Security Planning
In-depth guides in this section
TIMING
When to Claim Social Security: 62 vs. 67 vs. 70 - The Breakeven Math
Read the guide → (coming soon)
COUPLES
Spousal Benefits: How to Coordinate Social Security as a Couple
Read the guide → (coming soon)
SURVIVORS
Survivor Benefits: What Your Spouse Needs to Know
Read the guide → (coming soon)
TAXES
How Much of Social Security is Taxable?
Read the guide → (coming soon)
MEDICARE
Social Security and IRMAA: The Hidden Medicare Connection
Read the guide → (coming soon)
YOUR STATEMENT
How to Reach Your Social Security Statement
Read the guide → (coming soon)
MISTAKES
Social Security Mistakes that Cost Retirees $100,000 or More
Read the guide → (coming soon)
COMMON QUESTIONS
Frequently Asked Questions
Q What is the best age to claim Social Security?
There is no universal "best age" — it depends on your health, life expectancy, income from other sources and spousal situation. The breakeven between claiming early versus delaying typically falls in the late 70s to early 80s. For married couples, the higher earner's claiming age also determines the survivor benefit — which makes the household analysis even more important. Rob Field runs individualized Social Security analyses for every Nelson client to identify the strategy that makes the most sense for their specific situation.
Q Can I collect Social Security and still work?
Yes — but if you claim before your Full Retirement Age, the earnings test reduces your benefit by $1 for every $2 earned above $24,480 (2026 limit). After reaching FRA, there is no earnings penalty. Withheld benefits are recalculated and credited back over time, which affects the breakeven calculation. If you plan to keep working, this interaction is an important part of the decision.
Q How does Social Security affect my Medicare premiums?
Social Security income is included in Modified Adjusted Gross Income for IRMAA purposes. If combined income pushes MAGI above the threshold — $109,000 single, $218,000 joint in 2026 — Medicare Part B and Part D premiums increase for a full year. Rob Field holds both the NSSA and IRMAA Certified Planning designations, which means he models the Social Security decision and the Medicare premium interaction together, not separately.
Q How do I get Social Security analysis?
Schedule a free retirement strategy review with our team - click here or give our team a call. Rob Field will review your Social Security statement and model multiple claiming scenarios using your actual numbers. No account minimums. No obligation.
Get a personalized Social Security analysis - no cost, no obligation
Rob Field is the only Certified Financial Fiduciary in Florida with both NSSA® and IRMAA Certified Planning credentials.
Let's look at your numbers together.
Not quite ready?
Start with Dollars & Sense.
This is the same team, the same research, the same plain-English approach — every week on Central Florida radio and everywhere you listen to podcasts. The Morningstar X-Ray, ETF vs. mutual fund research, Social Security timing, investor psychology, tax strategy — it is all there. Ranked Top 25 in financial planning nationally, with over 50,000 downloads.
Listen to Dollars & Sense → Available on Spotify, Apple Podcasts, YouTube
Joel J. Garris is President and CEO of Nelson Financial Planning, Inc. and a FINRA Registered Representative with Nelson Ivest Brokerage Services, Inc. Investment advisory services through Nelson Advisory Services, Inc., a State of Florida registered investment advisor. Content is for informational purposes only and does not constitute personalized investment, tax, or legal advice.
Joel Garris, CFP, Certified Financial Fiduciary | Christina Lamb, IRS Enrolled Agent, Certified Financial Fiduciary | Kristin Kalley, CPA, CFP, Certified Financial Fiduciary | Rob Field, NSSA, IRMAA Certified Planning, Certified Financial Fiduciary | Zach Keister, Certified Financial Fiduciary, Chartered Retirement Planning Counselor | Chet Cowart, Certified Financial Fiduciary, Chartered Retirement Planning Counselor
www.NelsonFinancialPlanning.com | 407-307-3061 | Winter Park / Orlando, FL
Investment advice offered through Nelson Financial Planning. Past performance is not indicative of future results. The Morningstar X-Ray portfolio analysis is provided as an educational service and does not constitute investment advice or a solicitation. Nelson Financial Planning is a fiduciary firm — every advisor is a Certified Financial Fiduciary, legally required to act in the client's best interest. No account minimums.